Beyond trade volumes
By Sameer Gaikwad, Kline + Company | TLT Market Trends September 2026
How utilization and volatility are rewriting marine lubricant growth strategies.
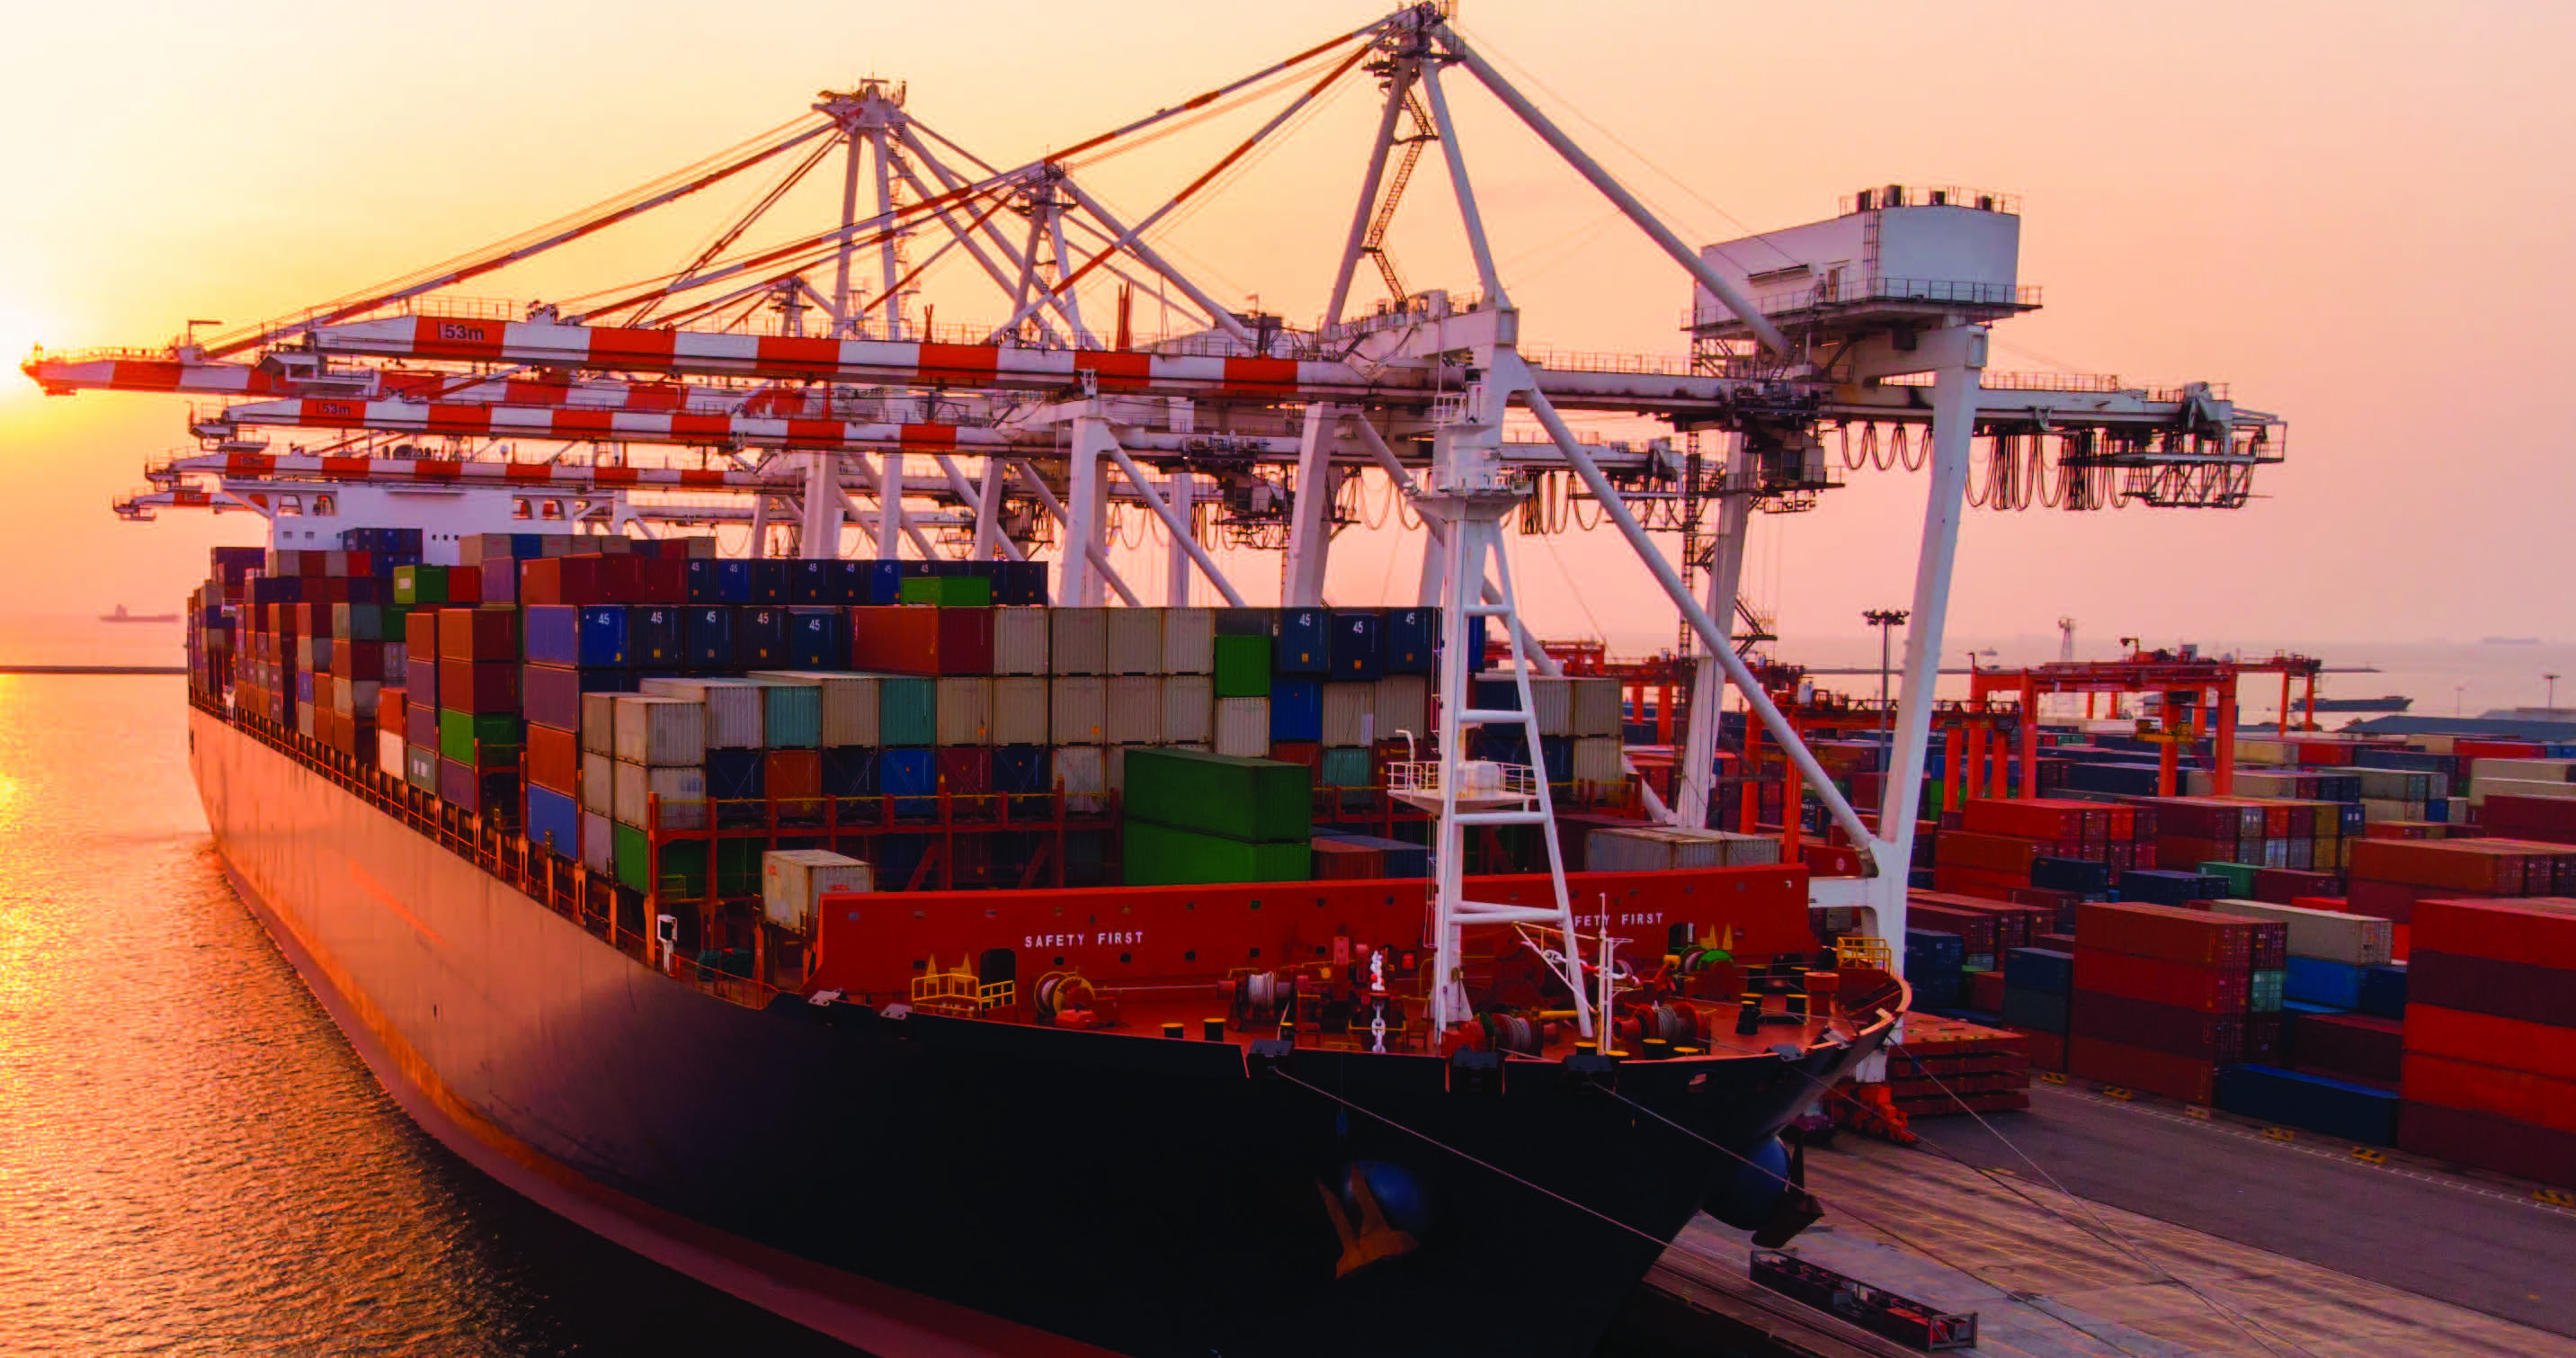
Suppliers already account for key operational drivers such as vessel utilization, voyage time and trading distances when shaping demand outlooks. What is changing today is not their understanding, but the market itself, where lubricant demand is increasingly diverging from trade growth trends.
Two forces are driving this shift. The first is utilization intensity: longer voyages, aging fleets and higher engine hours per vessel are pushing consumption upward even when cargo volumes stay flat. The second is systemic volatility: geopolitical shocks, base oil cost spikes and pricing instability are reshaping how suppliers contract, plan and protect margins.
However, if marine lubricant marketers continue to plan for normal growth trajectories, they risk missing both the volume opportunities and the margin threats that are already here. In this article, I will walk through what Kline + Company has observed on both fronts and then outline what we think marketers need to do differently. However, the situation is clearly still evolving.
The utilization shift: Why demand is growing without trade growth
Longer voyages, more engine hours: Currently, geopolitical disruptions, particularly the continued insecurity in the Red Sea and the closure of the Strait of Hormuz, have forced widespread rerouting via the Cape of Good Hope. This is no longer a temporary measure managed by a handful of operators; it is increasingly embedded into scheduling, freight procurement, bunker planning and port-call strategy across tanker and liner networks.
We have investigated the operational impact, and the numbers are significant. Asia–Europe transit times are up more than 20%, from roughly 37 days to 45-48 days. Voyage distances have extended by thousands of nautical miles, and bunker fuel consumption per trip has increased by approximately 35%. More days at sea means more engine running hours, which translates directly into higher lubricant consumption per voyage, even if the number of voyages or the cargo tonnes shipped remain flat.
This is structural, not cyclical. As long as key routes remain disrupted or unreliable, utilization intensity stays elevated. Rerouting has become the base case.
The aging fleet factor: Meanwhile, the global fleet is aging. A growing proportion of vessels are now 15 years or older. Older ships require more frequent maintenance, higher lubricant dosing rates and shorter drain intervals to maintain reliability. This demographic shift adds sustained upward pressure on demand, independent of new ship orders or scrapping rates. Marketers can no longer assume demand tracks fleet size alone: fleet composition and age profile matter equally.
Volume growth in a flat market: Even if global seaborne trade growth is flat or weak, the marine lubricants market can experience organic volume growth driven solely by operational intensity. This creates a hidden growth pocket. Suppliers who recognize and target high-utilization segments, long-haul routes, older fleets and rerouted traffic can capture incremental volumes that competitors still using traditional models will miss. Utilization-led demand is, in our view, the new baseline.
The volatility reality: Instability as the new operating environment
Base oil cost shocks and pricing pressure: On the cost side, the situation remains challenging. Marine lubricants rely heavily on Group I and II base oils, which have also witnessed price increases due to supply disruptions, refinery outages and geopolitical uncertainty. At the same time, volatility is more pronounced in Group III markets, creating broader pricing pressure across the system. Concerns around potential refinery output shifts and tighter availability are further driving buying urgency, with shipping companies often prioritizing supply security over price.
The commercial impact is significant. Price guarantees are shrinking from quarters to weeks, with more frequent repricing and contract renegotiations. Margins are being squeezed, as slow cost pass-through hurts profits, while aggressive pricing risks customer loss. This is not a short-term disruption. Volatility is becoming a structural feature, supported by geopolitical risks, supply chain disruptions and energy market instability.
Demand volatility; stockpiling and idle capacity: Demand itself is also volatile. Ship operators engage in precautionary stockpiling during crisis periods, boosting short-term offtake, then cut purchases when vessels are idled or tensions ease. This creates unpredictable spikes and troughs that complicate inventory planning and sales forecasting. Planning cycles are shorter, forecasting accuracy is lower and suppliers face working capital strain from swings in inventory and receivables.
The end of predictable contracts: In this environment, traditional annual contracts with fixed pricing are increasingly difficult to sustain. Suppliers and customers are moving toward dynamic pricing mechanisms, fuel surcharges, index-linked pricing and shorter contract terms. This raises transaction costs and demands more frequent commercial negotiations. However, it also creates opportunities. Suppliers who offer transparent, flexible pricing models and supply reliability can differentiate and retain customers even amid turbulence. Insurance and compliance constraints, such as higher war-risk premiums, enhanced due diligence and tighter voyage approvals, add further operational friction that ripples through schedules and port windows.
Strategic implications: What marketers must do differently
Based on what we have analyzed, four actions stand out.
Rethink segmentation and targeting: The traditional approach of segmenting by geography or vessel type is no longer sufficient. There is a need to shift toward utilization- and intensity-based segmentation: identifying vessels on rerouted long-haul routes, older fleets with elevated maintenance needs and operators running higher engine hours. Voyage data and fleet age profiles, not just tonnage or fleet size, should drive demand forecasts and sales resource allocation. The growth payoff is capturing incremental volumes invisible to competitors still relying on traditional models.
Build pricing and margin resilience: Adopting dynamic pricing frameworks that allow rapid cost pass-through while maintaining customer trust is crucial. Index-linked pricing, fuel surcharges and quarterly review clauses can protect margins during cost spikes. Transparent communication with customers about cost drivers is important. Clarity can prevent churn even when prices rise. In volatile markets, defending margin per unit may be more strategic than chasing volume share at any price.
Strengthen distribution agility and supply reliability: Supply chain flexibility and port-level service reliability are now competitive differentiators. Operators increasingly avoid single-point dependency, splitting bunkers and lubricant liftings across alternative hubs when feasible. Suppliers need broad port coverage, including secondary hubs gaining volume from rerouted traffic, and strategic inventory buffers to absorb demand spikes. Winning and retaining customers on service excellence, not only price, is a critical edge when competitors falter on delivery.
Prepare the portfolio for long-term shifts: While addressing near-term volatility, it is also important to begin portfolio adaptation for emerging technical demands, such as alternative fuels, stricter emissions regulations and advanced formulations. Investing in R&D and OEM partnerships now ensures readiness when regulatory or fuel-transition tailwinds accelerate demand for premium, specialized products.
This article is adapted, by permission, from Kline's Marine Industry Monitor and Marine Lubricants Market Report. To read the original reports, visit www.klinegroup.com.
Sameer Gaikwad is Project Lead at Kline + Company, specializing in marine lubricants and shipping industry analysis. You can reach him at sameer.gaikwad@klinegroup.com. Kline + Company is an international provider of world-class consulting services and high-quality market intelligence for industries including lubricants and chemicals. Learn more at www.klinegroup.com.